The clients I work with have dedicated years to building their wealth and securing their family’s future. Navigating your peak earning years means you are likely facing a critical milestone: finalizing your retirement strategy while simultaneously funding your children’s college education. A sophisticated financial plan must support both of these goals seamlessly.
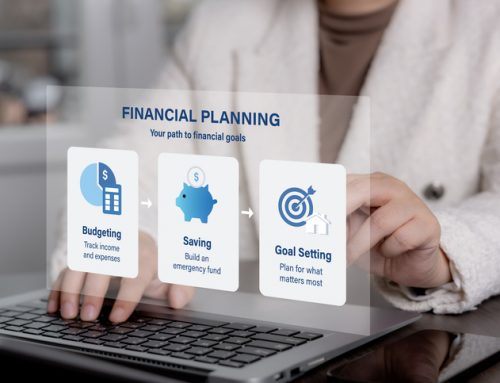
Too often, I see parents treating these milestones as competing interests. They unnecessarily drain their hard-earned nest egg to pay for tuition or take on debt that delays their retirement timeline. The core concept follows: College funding, aid eligibility, and retirement planning must work in tandem to protect your portfolio.
The Two Buckets of College Funding
When it comes down to it, every family has two buckets to fund college: assets and borrowing. Your assets could include savings, investments, and 529 plans, while borrowing often means taking a federal or private loan or borrowing against your home’s equity. For many families planning for college, both buckets are necessary to cover the rising costs of higher education.
However, traditional saving vehicles often involve specific trade-offs. For instance, accumulating assets in a 529 plan can increase your Student Aid Index, which may lower your financial aid eligibility. If your assets are parked in highly reportable buckets, they are heavily assessed by financial aid formulas, inflating what you are expected to pay out-of-pocket.
Mitigating Longevity Risk While Optimizing Aid
Your comprehensive plan must account for longevity risk, which is the possibility of outliving your assets in retirement. Can you afford to jeopardize your future security simply to cover a college tuition bill?
Fortunately, the retirement tools designed to mitigate longevity risk can simultaneously optimize your college aid profile.
Looking at alternative strategies, such as certain life insurance products, may help fund college expenses while supporting aid eligibility. As an asset, the cash value within a life insurance policy is often treated differently by financial aid formulas. Moving these funds over a multi-year period into alternative structures, such as cash value life insurance, offers a different approach. This strategy can help reduce the assessable asset base on financial aid forms to zero. Properly structured permanent life insurance provides accessible, non-reportable cash value that you can use for tuition, all while allowing your primary retirement accounts to continue compounding. At the same time, it allows capital to grow while helping protect it from market volatility and gives families the ability to access cash value through policy loans to help cover educational expenses. As an alternative borrowing source, life insurance policy loans can offer flexibility compared to traditional student debt.
Looking at the Bigger Picture
Balancing college expenses with retirement preservation is an important part of your long-term financial health. You wouldn’t execute a corporate merger without a comprehensive financial model, and funding higher education requires the same foresight. Let our team help you fund education while protecting your long-term security. Request your Free College Planning Analysis today.
Sources:
https://www.allianzlife.com/what-we-offer/Life-Insurance/College-Funding
https://www.savingforcollege.com/article/what-you-can-pay-for-with-a-529-plan
https://www.smartasset.com/student-loans/will-529-plan-affect-financial-aid